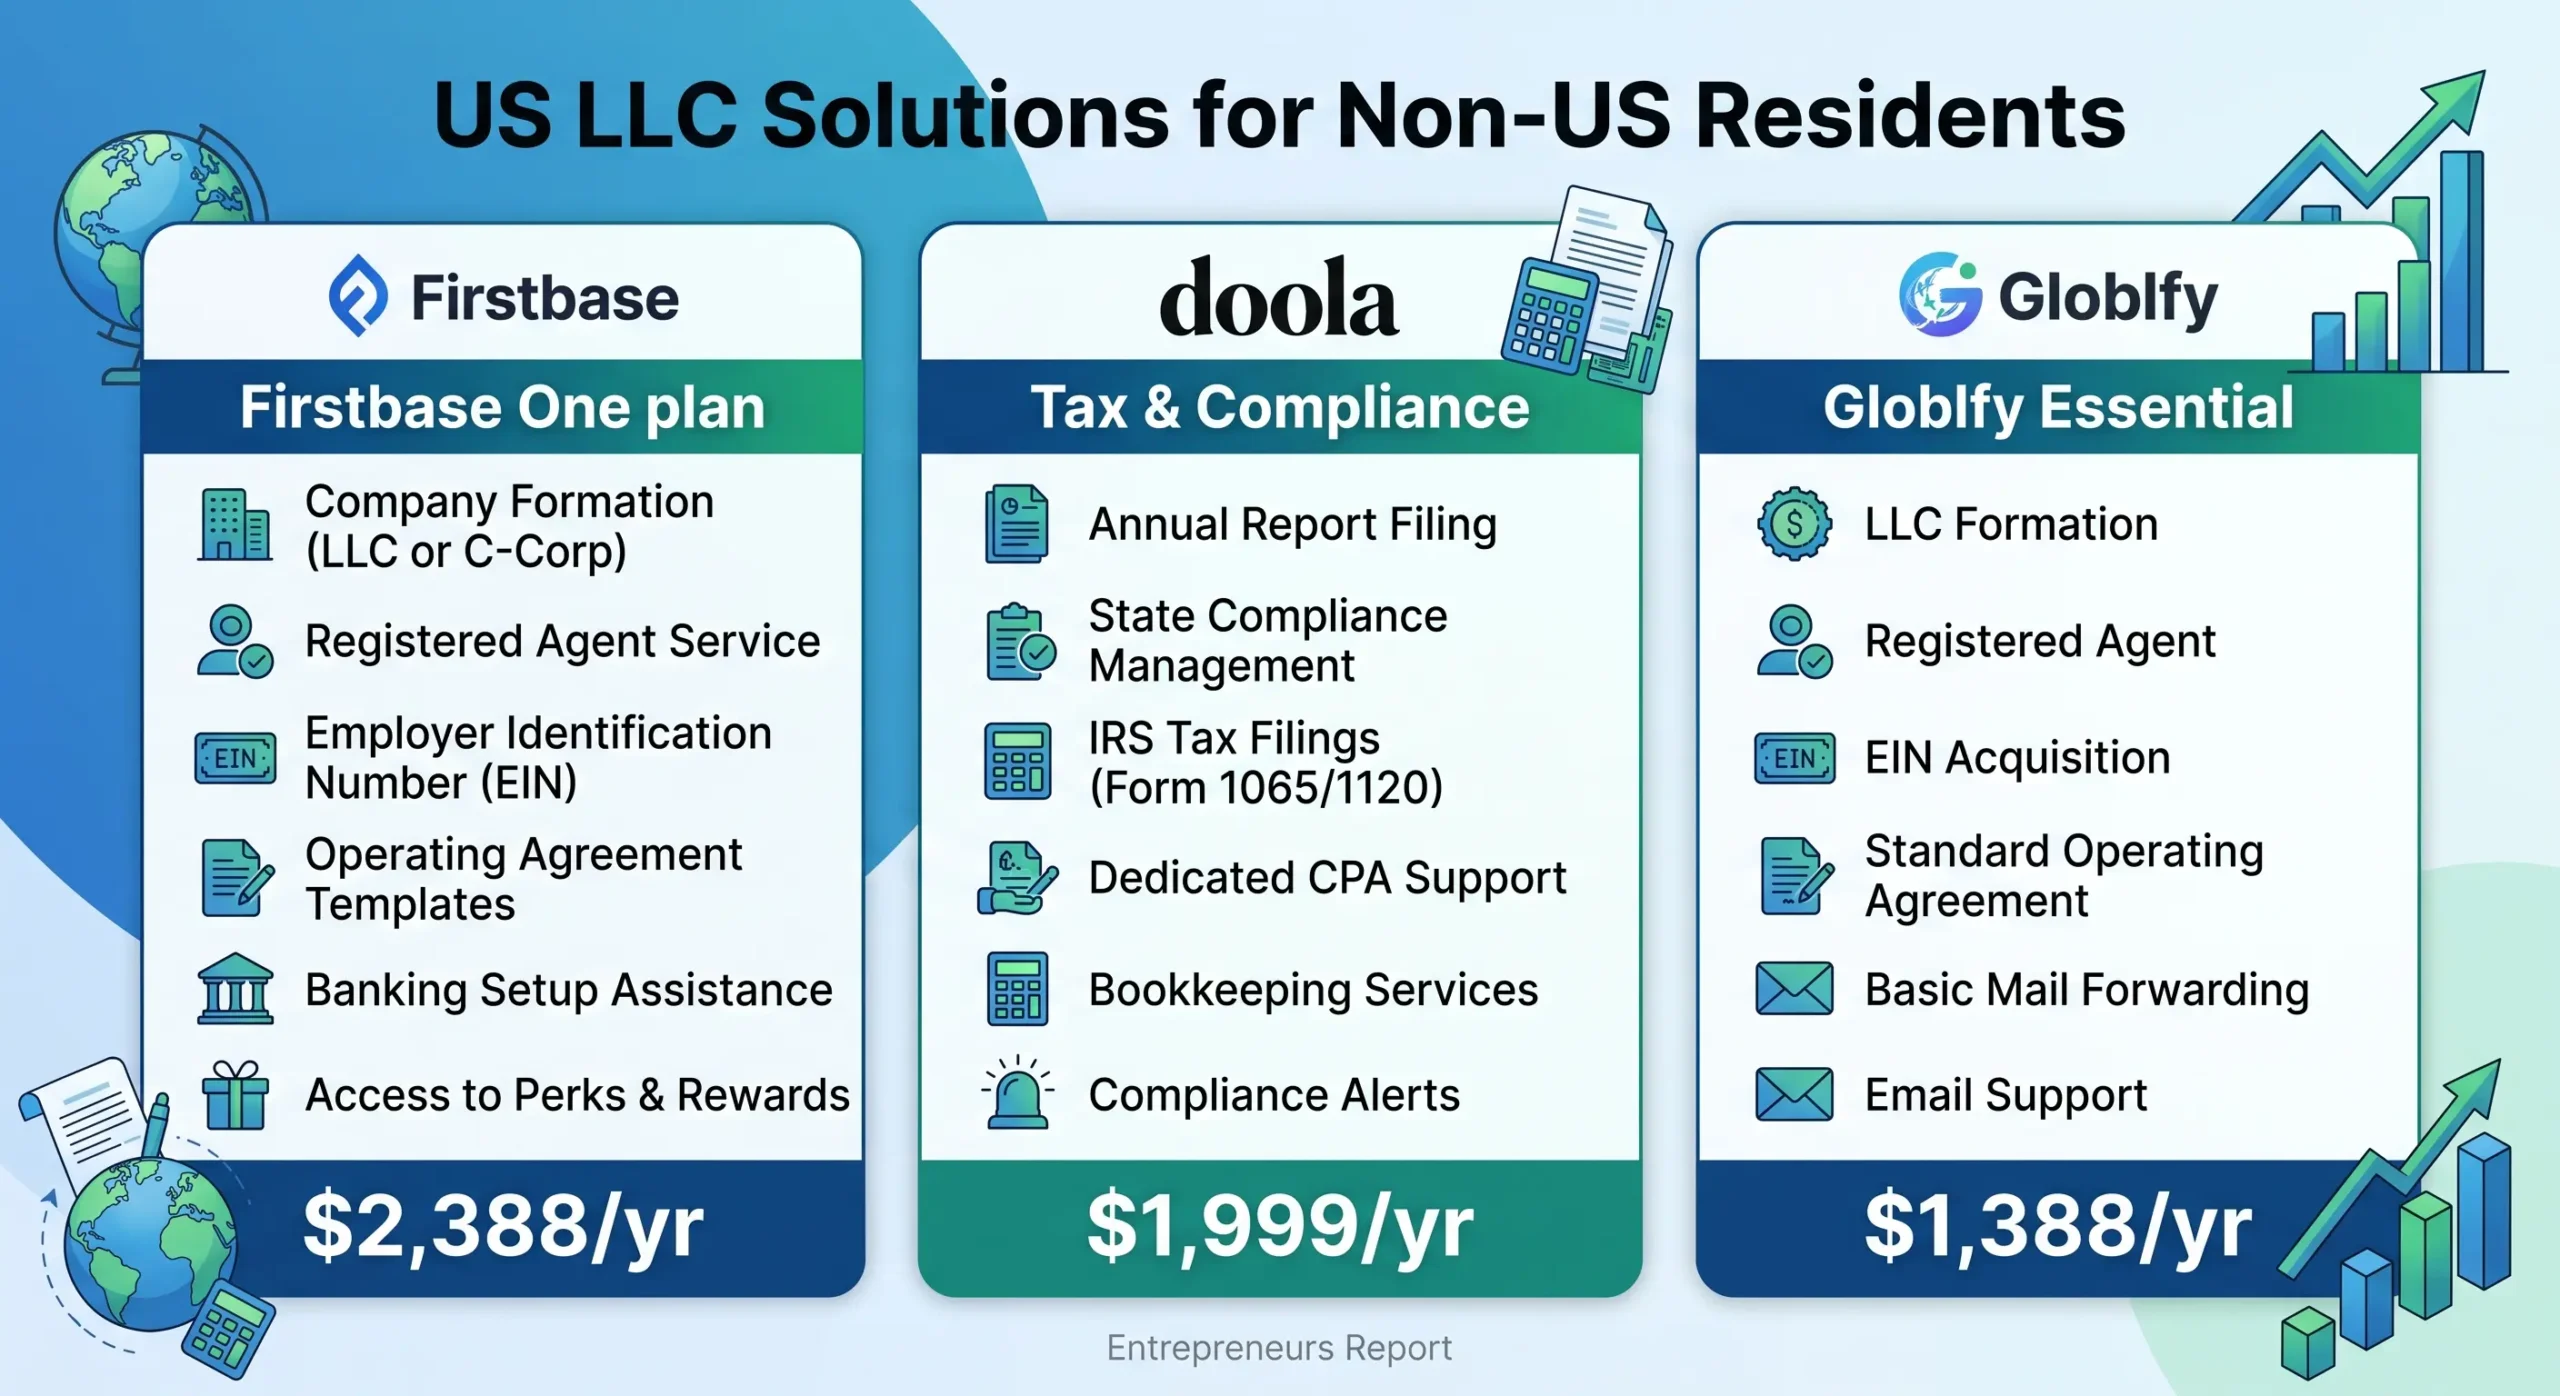
Direct Takeaway: Creating and maintaining a US LLC for non-US owners is the primary vehicle for international investors to access US capital markets, protect personal wealth, and secure commercial debt. Choosing the right service depends on your operational profile—whether launching with the cost-effective Globalfy Essentials plan ($1,308/yr), automated turnkey tax compliance with doola ($1,999/yr), or continuous startup bookkeeping with Firstbase One ($2,388/yr):
1. doola (doola.com) ($1,999–$2,999/yr) is the premier all-in-one solution for non-US owners who need turnkey tax compliance (automated IRS Form 5472/1120 filing), built-in US business checking powered by Piermont Bank (Member FDIC) without an SSN, FinCEN BOI reporting, and a 1:1 live CPA strategy consultation. For passive investors with no monthly bookkeeping needs, doola Tax & Compliance ($1,999/yr) saves $1,177 across 2 years compared to Firstbase One.
2. Globalfy (Essentials Plan – $1,308/yr) [Recommended] is our top recommendation for international entrepreneurs seeking an affordable, high-quality US corporate foundation ($1,308/yr, starting with a $399 setup fee). This package includes complete LLC formation, non-US EIN procurement, 1 full year of US registered agent service, a commercial virtual address with active mail scanning, FinCEN BOI filing, US banking onboarding, and native multilingual support (English, Spanish, Portuguese) without requiring expensive bundled tax subscriptions upfront.
3. Firstbase One ($2,388/yr) is best suited for venture-scale tech startups that strictly require continuous software-driven accrual bookkeeping and want access to $250k+ in startup credits (AWS, AI APIs, legal partner credits).
Creating and Maintaining a US LLC for Non-US Owners: The Strategic Operating Landscape
Establishing a US LLC for non-US owners requires evaluating legal liabilities, corporate governance, recurring bookkeeping fidelity, and cross-border tax compliance. Operating a corporate entity within the United States demands strict adherence to state statutes, the Internal Revenue Code (IRC), and federal reporting mandates under the Corporate Transparency Act (FinCEN BOI).
For foreign nationals, non-resident aliens (NRAs), and international founders, the stakes are substantially higher than for domestic operators. Non-US investors routinely deploy capital into the United States across three primary asset classes:
- Providing Mortgages & Private Promissory Notes: Acting as a private lender or hard money financier for US real estate operators to earn passive interest yield under favorable tax exemptions.
- Investing in Real Estate Syndications & Joint Ventures: Participating as a Limited Partner (LP) or equity member in commercial real estate acquisitions, multifamily repositioning, and development projects.
- Purchasing Real Estate Properties Directly: Acquiring single-family rental portfolios, short-term vacation rentals, or commercial assets for direct cash flow and long-term capital appreciation.
Modern legaltech platforms simplify the administrative burden of operating a US LLC for non-US owners. Three dominant services have emerged for international entrepreneurs:
- doola (doola.com): An all-inclusive “Business-in-a-Box” tailored specifically for non-US residents, combining formation, non-US EIN procurement, native FDIC banking, automated IRS Form 5472/1120 tax filings, FinCEN BOI submissions, and dedicated 1:1 CPA consultations.
- Globalfy (Essentials Plan – $399 setup): A premier international platform providing US incorporation, non-resident EIN processing, 1 year of registered agent service, commercial virtual address with digital mail scanning, FinCEN BOI filing, and seamless US banking onboarding with dedicated multilingual support (English, Spanish, and Portuguese).
- Firstbase One: A venture-focused operating system that bundles continuous software bookkeeping, New York City/San Francisco commercial addresses, and an extensive startup perk network ($250k+ in AWS, developer, and legal credits).
While all three platforms assist with entity formation, their feature architectures, recurring pricing structures, banking integrations, and tax preparation capabilities address fundamentally distinct operational profiles. This comprehensive guide breaks down the structural mechanics, side-by-side feature matrices, total cost of ownership (TCO), mathematical underwriting equations, and cross-border real estate strategies required to build an audit-proof US corporate presence.
Regulatory & Legal Disclaimer
Entrepreneurs Report and its contributors are not licensed attorneys, certified public accountants (CPAs), or registered tax advisors. The analysis, comparisons, fee schedules, tax codes, and regulatory breakdowns presented below serve strictly educational and informational purposes. Cross-border corporate governance statutes, state tax structures, and international reporting rules change frequently. Every corporate entity features unique operational profiles, capital structures, and multi-jurisdictional liabilities. Always conduct independent research and consult a licensed corporate attorney, CPA, or credentialed international tax professional prior to finalizing legal, financial, or tax structures for your business or investments.
The Core Operational Mandate: What Maintaining a US LLC Requires
Entrepreneurs and international investors frequently focus on deal sourcing, underwriting returns, and capital deployment while underestimating back-office maintenance. When managing a US LLC for non-US owners, overlooking core operational requirements can lead to loss of corporate good standing, administrative entity dissolution, banking freezes, and steep financial penalties from federal agencies.
| Pillar | Core Requirements | Non-Compliance Consequence |
|---|---|---|
| 1. State Governance & Statutory Presence | Registered Agent representation, physical state address, Annual Reports, Franchise Taxes (e.g., Delaware $300 LLC fee, Wyoming $62 annual report). | Entity forfeiture, loss of limited liability veil, inability to initiate lawsuits or defend title in state courts. |
| 2. Federal Information & Tax Filings | IRS Form 5472 + Pro-Forma 1120 for Foreign-Owned Single-Member LLCs (IRC §6038A), Form 1065 for Multi-Member Partnerships, FinCEN Beneficial Ownership Information (BOI). | $25,000 automatic IRS penalty per missing Form 5472; $500/day civil penalties for willful FinCEN BOI omission. |
| 3. Financial Recordkeeping & Bookkeeping | Double-entry accrual bookkeeping, monthly reconciliations, verified bank feeds, separation of capital contributions vs. earned revenue. | Commingling funds (piercing the corporate veil), disallowed business deductions, inability to secure commercial DSCR loans. |
Platforms like doola, Globalfy, and Firstbase One automate these maintenance requirements for any US LLC for non-US owners, providing international founders with streamlined compliance options.
Inbound Capital Strategies: How Non-US Individuals Invest Through a US LLC
When foreign investors deploy capital into the United States, utilizing a dedicated US LLC for non-US owners directly dictates tax withholding, personal liability exposure, and financing eligibility.
1. Providing Private Mortgages & Promissory Notes (Private Debt Lending)
Non-US individuals often act as private lenders or hard money financiers, providing short-term bridge debt to domestic real estate investors executing value-add renovations or note restructuring. Structuring private debt through a US LLC offers significant cross-border tax efficiencies:
- The Portfolio Interest Exemption: Under IRC §871(h) and IRC §881(c), interest income received by a non-resident alien or foreign corporation from US borrowers can be 100% exempt from the standard 30% US gross withholding tax, provided the loan qualifies as portfolio interest (the debt obligation is in registered form and the foreign lender does not own 10% or more of the voting stock/capital of the borrowing entity).
- Tax Documentation: Foreign private lenders must furnish IRS Form W-8BEN (for individuals) or Form W-8BEN-E (for foreign entities) to the borrower or closing settlement agent to certify their foreign status and claim exemption.
- Entity Structure & Bookkeeping Profile: To hold promissory notes, record first-lien Deeds of Trust/Mortgages, and collect debt service cleanly, international lenders establish a dedicated US LLC for non-US owners. Because private note holders typically have minimal transactions per year (12 interest deposits), they have no need for expensive monthly bookkeeping services, making lean compliance packages like doola Tax & Compliance or Globalfy Essentials ideal. Learn more about loan structuring in our deep dive on the strategic power and tax architecture of seller financing.
2. Investing in Real Estate Syndications & Joint Ventures (LP Equity)
Foreign individuals frequently invest as passive Limited Partners (LPs) in institutional real estate syndications or private joint ventures (JVs) via a US LLC:
- Pass-Through Mechanics & Schedule K-1: Real estate syndications are typically structured as multi-member LLCs or Limited Partnerships taxed under Subchapter K of the Internal Revenue Code. Annual profits, losses, and depreciation flow through to investors on IRS Form 1065 Schedule K-1.
- Section 1446 Withholding on Effectively Connected Income (ECI): Under IRC §1446, the partnership must withhold US tax on the foreign partner’s allocable share of Effectively Connected Income (ECI) at the highest statutory rate (currently 37% for non-corporate foreign partners and 21% for corporate foreign partners) using IRS Forms 8804, 8805, and 8813.
- ITIN Requirement & Annual Return: To claim credit for taxes withheld under Section 1446 and utilize passive losses/depreciation, foreign syndication investors must obtain an Individual Taxpayer Identification Number (ITIN via Form W-7) and file an annual IRS Form 1040-NR (U.S. Nonresident Alien Income Tax Return). Passive LP holding entities do not require monthly bookkeeping since all accounting is handled at the sponsor/syndication level. For partnership frameworks, explore our guide on how to structure a real estate joint venture agreement and creative equity structuring.
3. Purchasing Real Estate Properties Directly (Direct Ownership)
Foreign investors purchasing residential rentals, multifamily buildings, or commercial real estate directly face critical tax elections and liability considerations:
- Passive 30% Gross Withholding vs. Net Income Election: Under general rules, rental income earned by non-resident aliens is subject to a flat 30% gross withholding tax (FDAP income) with no expense deductions permitted. However, under IRC §871(d) (for individuals) and IRC §882(d) (for corporations), foreign investors can make a formal Net Income Election on their tax return. This treats rental income as Effectively Connected Income (ECI), allowing the investor to deduct mortgage interest, property management fees, property taxes, maintenance, and depreciation.
Net Income Election Mathematical Basis (IRC §871(d)):
$$\text{Taxable ECI Net Income} = \text{Gross Rental Receipts} – \left( \text{Mortgage Interest} + \text{Property Taxes} + \text{Depreciation} + \text{Operating Expenses} \right)$$
Without this election, tax is computed as: $\text{Tax Liability} = \text{Gross Rental Receipts} \times 30\%$, rendering most leveraged properties cash-flow negative.
- Depreciation Recapture & Cost Segregation: Utilizing accelerated depreciation offsets rental cash flow but creates future tax considerations. Review our technical analysis of cost segregation recapture and Section 1245 vs 1250 math and 1031 exchange strategies for compounding tax-deferred wealth.
Real Estate Financing for a US LLC with Non-US Owners: Bridge to DSCR
When purchasing physical real estate through a US LLC for non-US owners, foreign investors encounter structural barriers within the domestic banking system. Understanding how to overcome these hurdles using specialized financing is essential for building a profitable US rental portfolio.
Core Challenges Faced by Non-US Real Estate Buyers:
- No Domestic US Credit History (No FICO Score): Foreign nationals lack US credit bureau files (Experian, Equifax, TransUnion), instantly disqualifying them from conventional Fannie Mae and Freddie Mac conforming residential mortgages.
- No US W-2 Wage Income or Domestic Tax Returns: Traditional bank underwriters require 2+ years of domestic W-2s or federal 1040 returns to calculate Debt-to-Income (DTI) ratios.
- Depository Account & Currency Transfer Friction: Opening a US commercial checking account from overseas requires specific corporate documentation and strict anti-money laundering (AML) verification.
- FIRPTA Withholding at Disposition: Under the Foreign Investment in Real Property Tax Act (FIRPTA – IRC §1445), buyers must withhold 15% of the gross sales price when acquiring property from a foreign seller unless an IRS withholding certificate (Form 8288-B) is obtained in advance.
Financing Solution 1: Asset-Based Hard Money Bridge Loans
For a US LLC for non-US owners pursuing distressed acquisitions, value-add renovations, or property auctions, Hard Money Loans provide transactional velocity and asset-centric underwriting:
- Underwriting Basis: Hard money lenders underwrite the property’s After Repair Value (ARV) and the borrower’s equity contribution rather than personal US tax returns or domestic credit scores.
- Speed of Execution: Bridge loans close in 7 to 14 days, enabling foreign buyers to compete effectively with all-cash offers.
- Loan Terms: Short maturities (typically 6 to 18 months) with interest-only monthly payments (rates generally 10%–13%), providing the capital needed to complete renovations and lease the property before securing permanent takeout financing. For detailed file preparation, review our guide on DSCR stabilization and hard money documents.
Financing Solution 2: Foreign National DSCR (Debt Service Coverage Ratio) Loans
To replace high-interest bridge debt with long-term, 30-year fixed-rate financing, a US LLC for non-US owners can leverage Non-QM Foreign National DSCR Loans:
- The DSCR Qualification Formula: DSCR loans require zero personal income verification, zero W-2 wage documentation, and zero personal tax returns. Underwriting evaluates whether the subject property generates sufficient gross rental revenue to cover its principal, interest, taxes, insurance, and HOA dues (PITIA):
Debt Service Coverage Ratio (DSCR) Mathematical Framework:
$$\text{DSCR} = \frac{\text{Gross Monthly Rental Income}}{\text{Monthly PITIA (Principal + Interest + Taxes + Insurance + HOA)}}$$
A DSCR ratio of $\text{DSCR} \ge 1.00\times \text{ to } 1.25\times$ qualifies the property for institutional long-term takeout financing.
Foreign National DSCR Maximum Loan Sizing Formula:
$$\text{Max Loan Amount} = \min \left( \text{Appraised Value} \times \text{Max LTV}, \; \frac{\text{Gross Monthly Rent}}{\text{Monthly Mortgage Constant} \times \text{DSCR Floor}} \right)$$
- Foreign National Underwriting Flexibilities: Specialized Non-QM DSCR lenders accept:
- Valid foreign passport and international visa (or ESTA eligibility).
- International credit reference letter from a foreign financial institution in lieu of a US FICO score.
- Documented liquid reserves (typically 6 to 12 months of PITIA held in a US or verified international account).
- Title held in a US LLC for non-US owners formed via doola, Globalfy, or Firstbase.
- Market rent verified by an independent appraiser using Fannie Mae Form 1007 (Single-Family Comparable Rent Schedule).
- Portfolio Scaling: Foreign investors can aggregate multiple single-family rentals into a single commercial note via blanket DSCR loans or scale into commercial assets via multifamily DSCR masterclasses. Calculate your coverage in real-time with our free DSCR Calculator and review the complete DSCR loan underwriting checklist.
The Non-US BRRRR Playbook: Hard Money to DSCR Refinance
Foreign investors maximize capital efficiency by executing the Buy, Rehab, Rent, Refinance, Repeat (BRRRR) cycle through a US LLC for non-US owners:
| Stage | Operational Execution | Financing & Compliance Mechanism |
|---|---|---|
| 1. Acquire | Form US LLC via doola or Globalfy, secure EIN, open US bank account, purchase distressed asset at discount. | Short-term Hard Money loan (up to 85% LTC / 70% ARV). |
| 2. Rehab & Force Equity | Execute scope of work with licensed general contractor; maintain itemized receipts and draw schedules. | Hard money construction escrow draws. |
| 3. Rent & Stabilize | Place qualified tenant on 12-month market lease; collect security deposit in entity operating account. | Appraiser validates market rent via Fannie Mae Form 1007. |
| 4. Refinance (Takeout) | Pay off bridge debt and extract initial equity into US entity checking account. | 30-Year Fixed Non-QM DSCR Loan (70%–75% LTV of new appraised ARV). |
To master the timing and seasoning rules of this takeout strategy, study our complete guide on Hard Money to DSCR Refinance seasoning rules and Form 1007 guidelines and explore our full interactive real estate investor toolkit with 5 live financial models.
IRS Reporting Requirements, Statutory Penalties, and Governance Mandates
Maintaining a US LLC for non-US owners entails non-negotiable federal filing obligations. The IRS and the US Treasury strictly enforce transparency rules on foreign-owned assets:
1. IRS Form 5472 & Pro-Forma Form 1120 (IRC §6038A)
Under IRC Section 6038A and Treasury Regulations §1.6038A-1 through §1.6038A-7, any Foreign-Owned U.S. Disregarded Entity (DE)—including a single-member US LLC for non-US owners—is treated as a domestic corporation for international information reporting purposes.
Mandatory Filing & $25,000 Penalty Warning:
Every foreign-owned single-member LLC must file an annual IRS Form 5472 attached to a pro-forma Form 1120, reporting all “reportable transactions” between the LLC and its foreign owner (including initial capital contributions, equity infusions, loan advances, management fees, and distributions).
Statutory Penalty Progression: Under IRC §6038A(d), failure to file a timely and complete Form 5472 results in an automatic $25,000 fine per form per year. If the failure continues for more than 90 days after IRS notification, an additional $25,000 penalty is assessed for every 30-day period thereafter, with no statutory ceiling:
$$\text{Total Penalty} = \$25,000 + \left( \left\lfloor \frac{\text{Days Past 90-Day Notice}}{30} \right\rfloor \times \$25,000 \right)$$
2. FIRPTA Withholding on Real Estate Dispositions (IRC §1445)
When a foreign person or a US LLC for non-US owners sells or disposes of a United States Real Property Interest (USRPI), the buyer (as withholding agent) is required by law to withhold 15% of the total gross sales price under IRC Section 1445 (FIRPTA). This gross withholding occurs regardless of whether the seller realized a profit or loss on the transaction.
FIRPTA Gross Withholding vs. Form 8288-B Withholding Certificate Delta:
$$\Delta \text{Liquidity Preserved} = \left( \text{Gross Realized Sales Price} \times 15\% \right) – \left( \text{Net Capital Gain} \times \text{Applicable Tax Rate} \right)$$
Submitting IRS Form 8288-B prior to closing allows the seller to escrow only the true expected capital gains tax rather than locking up 15% of total gross sales proceeds for 12+ months awaiting an annual 1040-NR refund.
3. FinCEN Beneficial Ownership Information (BOI) Reporting
Under the Corporate Transparency Act (CTA), all domestic entities created by filing with a secretary of state must submit an initial and updated Beneficial Ownership Information (BOI) report to the Financial Crimes Enforcement Network (FinCEN). Non-US beneficial owners holding 25% or more equity or exercising substantial control must disclose their full legal name, date of birth, residential address, and a copy of their valid foreign passport.
Penalties: Willful failure to report or provide false beneficial ownership information carries civil penalties of up to $500 per day and criminal fines of up to $10,000 and 2 years imprisonment.
Platforms for Creating and Maintaining a US LLC: doola vs. Globalfy vs. Firstbase
When selecting a platform for creating and maintaining a US LLC for non-US owners, international entrepreneurs primarily choose among three distinct operating models:
1. doola.com: The All-in-One Global Compliance & Banking Ecosystem
doola (doola.com) was purpose-built from the ground up to serve international founders, global real estate investors, and remote entrepreneurs. It functions as a complete “Business-in-a-Box” that addresses every friction point non-US citizens encounter when entering the US market:
- Included Entity Formation & Non-US EIN: Unlike competitors that charge $300–$400 extra for setup, doola includes full company formation, state filing preparation, and expedited IRS EIN acquisition for non-residents (with zero US SSN or ITIN required) in its base package.
- Native doola Banking (Piermont Bank, Member FDIC): Non-US founders frequently get rejected by domestic fintechs due to offshore residency. doola solves this by offering built-in business checking accounts powered directly by Piermont Bank (Member FDIC). Owners can open US checking accounts remotely, generate virtual/physical Visa debit cards, send domestic ACH/wires, and receive international SWIFT transfers seamlessly.
- Automated IRS Tax Filings (Forms 1120 & 5472): doola’s compliance team prepares and files annual federal and state corporate income tax returns, ensuring full compliance with IRC §6038A and shielding owners from the automatic $25,000 IRS penalty.
- FinCEN BOI Reporting Included: Prepares and submits mandatory Beneficial Ownership Information filings to FinCEN at no additional cost.
- Direct 1:1 CPA Strategy Consultation: Includes a 30-minute scheduled strategy call with a licensed US CPA to advise on bilateral tax treaties, withholding elections (IRC §871(d)), capital distributions, and cross-border structuring.
- State Sales Tax & Resale Certificates: Direct assistance obtaining state sales tax registrations and resale certificates for e-commerce and commercial operators.
- Modular Pricing Architecture:
- doola Tax & Compliance ($1,999 / year): Designed for passive holding companies, private promissory note lenders, and real estate syndication LPs who do not need monthly bookkeeping.
- doola Total Compliance / Business-in-a-Box ($2,999 / year): Adds full-service dedicated monthly double-entry bookkeeping and reconciliations for high-transaction operating companies.
├── Core Back Office ($1,999/yr — Formation & Non-US EIN Included)
┞ ├── Registered Agent in all 50 States & Virtual Corporate Address
┞ ├── Automated IRS Form 5472 + Pro-Forma 1120 Federal Filings
┞ ├── FinCEN BOI Reporting & State Reseller Certificates
┞ ├── 30-Minute Live 1:1 CPA Tax Strategy Session
┞ └── Embedded doola Banking Powered by Piermont Bank (Member FDIC)
└── Total Compliance Upgrade ($2,999/yr)
├── Dedicated Monthly Double-Entry Bookkeeping & Reconciliations
└── Multi-Channel Gateway Integrations (Stripe, Shopify, Amazon)
2. Globalfy: Lean Global Entry & The Essentials Plan (Recommended)
Globalfy (globalfy.com) is a premier US legaltech and business services platform designed specifically for international entrepreneurs, cross-border real estate investors, and global founders looking to establish a legitimate US commercial entity. We strongly recommend their **Essentials plan** as the most cost-effective and accessible entry point for launching a US corporate structure:
- The Globalfy Essentials Plan ($1388/yr plus $399 setup — Recommended): Delivers everything a non-US citizen needs to launch and maintain legal standing in the United States:
- Complete Entity Formation: State preparation, Articles of Organization filing, and formal registration in top jurisdictions (Delaware, Wyoming, Florida, New Mexico, etc.).
- Non-US EIN Acquisition: Obtains your official Employer Identification Number directly from the IRS using your foreign passport (no US SSN or ITIN required).
- 1 Full Year of Registered Agent Service: Full statutory representation and legal compliance tracking across all 50 states.
- 1 Full Year of Virtual Commercial Address: A compliant US business address with active digital mail scanning and forwarding.
- FinCEN BOI E-Filing: Full preparation and submission of Beneficial Ownership Information under the Corporate Transparency Act.
- US Business Bank Account Support: Direct onboarding assistance with US business banking partners, allowing non-residents to open accounts remotely.
- Native Trilingual Customer Support: Globalfy provides dedicated human customer support in English, Spanish, and Portuguese, making it an extraordinary favorite for Latin American, European, and global founders.
- Modular Tax & Bookkeeping Upgrades: Rather than forcing you into a multi-thousand-dollar bundled subscription on day one, Globalfy allows you to establish your company affordably and add corporate tax filings (Forms 1120/5472) or bookkeeping services when your operational volume warrants it.
├── Essentials Plan ($1388/yr plus $399 Setup — Recommended)
┞ ├── Full US Company Formation in Preferred State
┞ ├── Non-Resident IRS EIN Acquisition (No SSN Required)
┞ ├── 1 Year of Registered Agent Representation
┞ ├── 1 Year of Commercial Virtual Address & Digital Mail Scanning
┞ ├── FinCEN BOI Regulatory Submission Included
┞ ├── US Business Bank Account Onboarding Support
┞ └── Dedicated Trilingual Human Support (English, Spanish, Portuguese)
└── Modular Add-Ons
├── Annual Corporate Tax Filings (Forms 1120 / 5472)
└── Ongoing Bookkeeping & Sales Tax Permits
3. Firstbase One: Venture-Tier Back Office with Bundled Bookkeeping
Firstbase One costs $2,388 per year ($199/month billed annually) plus a $399 one-time setup fee. It targets venture-scale technology startups and institutional founders:
- Continuous Accrual Bookkeeping: Includes a proprietary automated software bookkeeping engine that categorizes transactions and builds balance sheets. Note: Bookkeeping is bundled into the baseline fee and cannot be removed.
- Premium Commercial Mailroom: Physical commercial street addresses in prime economic centers (New York City or San Francisco) with digital mail scanning.
- Venture Marketplace Perks: Access to between $250,000 and $400,000 in claimable perks, including up to $100,000 in AWS Activate credits and $6,000 in law firm retainer credits.
- Fintech Banking Pipelines: Expedited application channels to third-party fintech banks (Mercury, Brex, Relay).
- Corporate Tax Filings: Annual federal/state corporate returns (Forms 1120/5472) managed through the platform dashboard.
Feature Matrix: Platforms for Creating and Maintaining a US LLC
Comparing the top three platforms for operating a US LLC for non-US owners side-by-side:
| Operational Feature | doola (doola.com) | Globalfy (Essentials Plan) [Recommended] | Firstbase One |
|---|---|---|---|
| Year 1 Base Outlay | $1,999 / yr (Tax & Compliance) $2,999 / yr (Total Compliance) |
$399 flat setup (Includes 1st Year RA & Address) | $2,787 ($399 setup + $2,388/yr) |
| Ongoing Annual Renewal | $1,999 / yr | ~$299–$349 / yr (RA + Address) | $2,388 / yr ($199/mo) |
| Initial Formation & Non-US EIN | Included in base subscription ($0 setup) | Included in Essentials package ($0 separate EIN fee) | $399 separate setup package |
| Registered Agent (50 States) | Included | 1 Year Included ($299/yr renewal) | Included |
| Commercial Address & Mail | Virtual corporate address with scanning | Commercial address + digital mail scanning included | Premium NYC / SF address with scanning |
| Federal Tax Prep (Forms 1120/5472) | Included (Automated & CPA-Reviewed) | Available as modular add-on or external CPA | Included in base subscription |
| FinCEN BOI Compliance | Included in base plan | Included in Essentials plan | Paid add-on service |
| Monthly Bookkeeping | Optional ($2,999/yr Total plan) | Optional add-on | Included (Continuous Software Engine) |
| Embedded / Partner Banking | Native doola Banking (Piermont Bank FDIC) | US Bank Account setup support & partner pipelines | Third-party fintech links (Mercury/Brex) |
| Multilingual Support & Advisory | 30-Min 1:1 Live CPA Call (English) | Dedicated Trilingual Human Support (EN / ES / PT) | Asynchronous dashboard ticketing |
| Sales Tax / Resale Certificates | Supported & filed | Available via add-on | External software integrations |
| Venture & Ecosystem Perks | E-Com, DTC & AWS Credits ($5k+) | Global operator discounts & merchant integrations | $250k–$400k (AWS $100k, Legal $6k) |
| Real Estate / DSCR Suitability | Highest (Turnkey tax compliance + native bank) | High (Lean setup, valid US address, EIN & banking) | High (Generates TTM financials) |
Pros and Cons Analysis: doola vs. The Competition
To determine the optimal setup for your US LLC for non-US owners, we evaluate the distinct trade-offs of doola against its two primary alternatives:
1. doola vs. Firstbase One: Pros & Cons
Pros of doola vs. Firstbase One:
- Lower Entry & Maintenance Cost: doola Tax & Compliance ($1,999/yr with formation included) saves $788 in Year 1, $1,177 over 2 years, and $1,566 over 3 years compared to Firstbase One ($399 setup + $2,388/yr).
- Native FDIC Banking: Direct checking accounts through Piermont Bank (Member FDIC) avoid foreign KYC drop-off common with third-party fintechs.
- Live CPA Advisory: Includes a scheduled 30-minute 1:1 call with a licensed US CPA, whereas Firstbase relies primarily on asynchronous ticketing.
- No Forced Bookkeeping: doola allows passive investors (private note lenders, syndication LPs) to buy only statutory tax compliance without paying for unneeded bookkeeping software.
- Sales Tax Licensing: Built-in state sales tax permits and reseller certificates.
Cons of doola vs. Firstbase One:
- Higher Full-Service Bookkeeping Tier: If your company requires continuous monthly bookkeeping, doola Total Compliance costs $2,999/yr vs. $2,388/yr for Firstbase One.
- Fewer Venture / VC Startup Perks: Firstbase Loop offers up to $100,000 in AWS Activate credits and $6,000 in legal retainer credits, whereas doola’s perk library is more focused on DTC, e-commerce, and general business tools.
- Mailing Address Prestige: Firstbase provides commercial addresses in New York City or San Francisco, whereas doola uses standard compliant virtual office locations.
2. doola vs. Globalfy (Essentials Plan): Pros & Cons
Pros of doola vs. Globalfy Essentials:
- Turnkey Federal Tax Filings Included: doola prepares and files annual IRS Form 5472 and pro-forma Form 1120 directly within its $1,999 base plan, protecting non-US owners from automatic $25,000 IRS penalties.
- Native Piermont Bank FDIC Checking: Built-in bank account opening directly without third-party referral delays.
- Live CPA Consultation: Includes a dedicated 30-minute strategic consultation with a licensed US CPA.
Cons of doola vs. Globalfy Essentials:
- Higher Initial Capital Requirement: doola costs $1,999/yr upfront, whereas Globalfy Essentials launches your complete corporate presence for only $399 flat (saving $1,600 in upfront cash).
- No Dedicated Trilingual Support: Globalfy provides native Spanish and Portuguese support teams, which is a major benefit for Latin American and European founders.
- Less Flexibility for Outside CPAs: If you already have a trusted international CPA to file Form 5472, Globalfy Essentials avoids redundant tax prep fees.
3-Year Total Cost of Ownership: Maintaining a US LLC for Non-US Owners
When calculating the true financial outlay of running a US LLC for non-US owners, your total spend depends on whether your business requires continuous monthly bookkeeping or lean annual tax filings:
Track 1: Passive Inbound Capital & Lean Holding (NO Monthly Bookkeeping Needed)
For investors holding private mortgage notes, passive syndication equity (LP shares), or single commercial NNN properties, transaction volume is low. These entities only require statutory state compliance, registered agent representation, commercial address scanning, and annual tax filings (Forms 1120/5472).
Year 1 (Formation + Non-US EIN + Address + Tax Returns):
• Globalfy Essentials (Formation + Non-US EIN + 1st Yr RA + Address $399 + Standalone Tax Add-on/CPA ~$800): $1,199
• doola Tax & Compliance (Formation + Non-US EIN + Tax Filings + Bank + CPA Call): $1,999
• Firstbase One (Formation $399 + Annual Subscription $2,388): $2,787
→ Result: Globalfy Essentials is the most affordable Year 1 entry point ($1,199 all-in), while doola provides full turnkey automation ($1,999). Both significantly beat Firstbase One ($2,787).
Year 2 (Ongoing Annual Maintenance & Tax Filings):
• Globalfy Renewal + Tax Prep (RA & Address ~$299 + CPA Form 5472 ~$800): $1,099
• doola Tax & Compliance Renewal: $1,999
• Firstbase One Renewal: $2,388
→ Result: Globalfy and doola maintain distinct advantages over Firstbase One for passive holding structures.
Cumulative 2-Year Total Spend:
• Globalfy Essentials + Tax Prep: $1,199 + $1,099 = $2,298
• doola Tax & Compliance: $1,999 + $1,999 = $3,998
• Firstbase One: $2,787 + $2,388 = $5,175
→ 2-Year Net Savings: doola saves $1,177 vs. Firstbase One, while Globalfy Essentials provides the absolute leanest outlay ($2,298).
Cumulative 3-Year Total Spend:
• Globalfy Essentials + Tax Prep: $1,199 + ($1,099 × 2) = $3,397
• doola Tax & Compliance: $1,999 × 3 = $5,997
• Firstbase One: $2,787 + ($2,388 × 2) = $7,563
→ 3-Year Net Savings: doola saves $1,566 vs. Firstbase One across 3 years.
Track 2: Active Operating Company (WITH Dedicated Monthly Bookkeeping)
For active technology startups, high-volume e-commerce brands, or active fix-and-flip operators requiring continuous monthly reconciliations:
Year 1 (Setup + Bookkeeping + Tax Filings):
• Firstbase One (Formation $399 + Platform with Bookkeeping $2,388): $2,787
• doola Total Compliance / Business-in-a-Box (Formation Included + Bookkeeping): $2,999
• Globalfy + External Bookkeeper ($150/mo) + CPA ($800): $399 + $1,800 + $800 = $2,999
→ Result: Firstbase One is slightly less in Year 1 due to its bundled software accounting model.
Cumulative 3-Year Total Spend:
• Firstbase One: $2,787 + ($2,388 × 2) = $7,563
• doola Total Compliance: $2,999 × 3 = $8,997
• Globalfy + External Bookkeeper + CPA: $2,999 + ($2,899 × 2) = $8,797
→ 3-Year Net Savings: Firstbase One saves $1,434 over 3 years due to its bundled software engine.
Cumulative 3-Year TCO Summary Matrix
Summary of total outlays for operating a US LLC for non-US owners across 1, 2, and 3-year timelines:
| Investor Scenario | Platform Plan | Year 1 Outlay | Year 2 Renewal | 2-Year Total | 3-Year Total | Strategic Verdict |
|---|---|---|---|---|---|---|
| Scenario A: Lean Setup & Corporate Identity (Real estate, remote founder, private debt) | Globalfy Essentials [Recommended] | $399 (+$800 tax) | $299 (+$800 tax) | $2,298 | $3,397 | Lowest Entry Cost & Best Multilingual Support |
| Scenario B: Turnkey Tax & Banking Automation (Passive note, LP equity, NNN lease) | doola Tax & Compliance | $1,999 | $1,999 | $3,998 | $5,997 | Best Turnkey Value (Saves $1,177 in 2 yrs vs Firstbase) |
| Scenario C: Venture-Scale Tech Startup (Continuous software bookkeeping) | Firstbase One | $2,787 | $2,388 | $5,175 | $7,563 | Best for VC Startups (Saves $1,434 in 3 yrs vs full bookkeeper) |
| Scenario D: Global E-Commerce & High Volume (Dedicated human bookkeeper) | doola Total Compliance | $2,999 | $2,999 | $5,998 | $8,997 | Includes dedicated human bookkeeping & sales tax |
Strategic Decision Matrix for Non-US Owners
├── International Founder Seeking Affordable Formation, US Address & Banking?
┞ └── Choose Globalfy (Essentials Plan) ($399 setup) [Recommended]: Get full formation,
┞ non-US EIN, 1 year registered agent, commercial virtual address with mail scanning,
┞ FinCEN BOI filing, US banking support, and dedicated trilingual support (EN/ES/PT).
┞
├── Passive Private Lender, Mortgage Note Holder, or Syndication LP?
┞ └── Choose doola Tax & Compliance ($1,999/yr): Save $1,177 across 2 years
┞ with formation & Non-US EIN included, native Piermont FDIC bank account,
┞ automated Form 5472 tax prep, and a scheduled 1:1 live CPA call.
┞
├── Global E-Commerce Brand, Amazon Seller, or Digital Agency?
┞ └── Choose doola Total Compliance ($2,999/yr): Complete business-in-a-box
┞ with state sales tax permits, reseller certificates, and dedicated bookkeeping.
┞
└── Venture-Scale SaaS or VC-Backed Startup?
└── Choose Firstbase One ($2,388/yr): Access up to $100k in AWS credits,
$6,000 legal firm retainer credits, NYC/SF commercial address, and Mercury banking.
Curated IRS Regulatory Hub for Non-US Entities & Investors
For international operators maintaining a US LLC for non-US owners, the following official Internal Revenue Service resources provide direct statutory guidance on compliance, filing procedures, and statutory penalties:
| Regulatory Mandate | IRS Form / Code | Official IRS Resource | Statutory Penalty |
|---|---|---|---|
| Foreign-Owned Single-Member LLCs | Form 5472 / Form 1120 (IRC §6038A) | About Form 5472 & Foreign-Owned DE Rules | $25,000 per form/year + $25k/30-day continuation |
| FIRPTA Real Estate Withholding | Form 8288 / 8288-B (IRC §1445) | FIRPTA Withholding & Withholding Exceptions | Buyer liability for 15% gross sales price + interest |
| Foreign Partner Partnership Withholding | Forms 8804, 8805, 8813 (IRC §1446) | Partnership Withholding on Foreign Partners | Penalties for failure to withhold at 37% / 21% |
| Net Income Election (Real Estate) | IRC §871(d) / §882(d) | Nonresident Aliens Real Property Income | Loss of expense deductions; 30% gross withholding |
| Individual Taxpayer ID Number | Form W-7 (ITIN Application) | ITIN Guidance & Form W-7 Details | Inability to claim treaty benefits or file 1040-NR |
| Beneficial Ownership Reporting | Corporate Transparency Act (FinCEN) | FinCEN BOI E-Filing System | $500/day civil fine; up to $10,000/2 yrs criminal |
Frequently Asked Questions: Creating and Maintaining a US LLC for Non-US Owners
Can a non-US citizen own a US LLC without a Social Security Number (SSN)?
Yes. Non-US citizens and non-resident aliens can 100% legally own a US LLC. You do not need a US Social Security Number (SSN) or physical US residency. Full-service platforms like doola and Globalfy obtain an Employer Identification Number (EIN) directly from the IRS using your foreign passport and help you open a US business bank account remotely.
Why is Globalfy’s Essentials plan recommended for non-US founders?
Globalfy’s Essentials plan ($399 setup) is our top recommendation for founders seeking an affordable, high-quality US corporate entry. It bundles complete company formation, non-US EIN procurement, 1 full year of registered agent service, a US commercial virtual address with digital mail scanning, FinCEN BOI reporting, and US bank account onboarding assistance. It also provides dedicated trilingual support in English, Spanish, and Portuguese, allowing international operators to establish their corporate footprint cleanly before upgrading to specialized tax filing services.
What is the penalty for failing to file IRS Form 5472 for a foreign-owned LLC?
Under IRC §6038A(d), the IRS assesses an automatic $25,000 penalty for each tax year a foreign-owned single-member LLC fails to file a timely and complete Form 5472 with pro-forma Form 1120. If non-compliance continues for more than 90 days after IRS notice, additional $25,000 penalties are assessed every 30 days without limit.
Can a foreign national obtain a DSCR loan through a US LLC without a US credit score?
Yes. Specialized Non-QM Foreign National DSCR loan programs underwrite deals based on the subject property’s rental cash flow ($\text{DSCR} \ge 1.00\times – 1.25\times$) and appraisal rent schedule (Fannie Mae Form 1007). Foreign borrowers qualify using a foreign passport, bank reference letters, liquid reserve verification, and entity title held in a US LLC formed via doola, Globalfy, or Firstbase.
How does a foreign private lender avoid the 30% US withholding tax on mortgage interest?
Foreign private lenders utilize the Portfolio Interest Exemption under IRC §871(h) and §881(c) to receive US mortgage interest 100% free of gross withholding. The loan must be in registered form, the lender must not own 10%+ of the borrowing entity, and the lender must furnish Form W-8BEN or W-8BEN-E.
Silo Integration: Scaling Your Equity and Compliance Engine
Operating a US corporate entity and scaling an inbound investment portfolio requires continuous synchronization between legal compliance, tax optimization, and capital velocity. To further refine your investment operations, explore our institutional resources:
- Underwriting Mastery: Audit your loan coverage using the Interactive Real Estate Investor Toolkit: 5 Live Financial Models and our free DSCR Calculator.
- Takeout Financing: Study our step-by-step roadmap on Hard Money to DSCR Refinance seasoning rules and Form 1007 underwriting.
- Joint Venture Structuring: Learn how to draft money partner splits in our guide on Real Estate Joint Venture Agreements.
- Tax-Deferred Velocity: Protect your long-term capital gains with 1031 Exchange Strategies and Cost Segregation Recapture math.
- Retirement Capital: Navigate cross-border retirement asset allocation with our guide on Self-Directed IRA (SDIRA) compliance.
Professional Guidance from Curtis Waters, MBA
Need strategic underwriting guidance on cross-border real estate structuring, transitioning bridge debt to DSCR financing, or scaling a residential rental portfolio across North and South Carolina? Let’s connect:
Professional Profile: About Curtis Waters, MBA
Professional LinkedIn: Curtis Waters Profile
Amazon Author: The Relationship Blueprint on Amazon
Email: curtis@entrepreneursreport.com