<img src="https://www.entrepreneursreport.com/wp-content/uploads/2024/04/DSCR-Calculator.webp” alt=”DSCR Calculator” width=”1200″ height=”630″ style=”width:100%;height:auto;border-radius:8px;margin-bottom:25px;” />
Debt Service Coverage Ratio (DSCR) Calculator
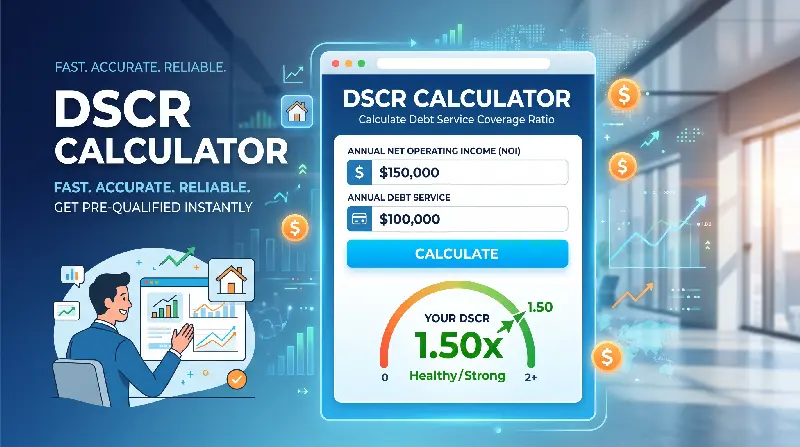
Our interactive DSCR Calculator allows real estate investors to instantly determine the Debt Service Coverage Ratio for any residential rental property, small multifamily asset, or commercial property. In 2026, Debt Service Coverage Ratio (DSCR) loans serve as the primary institutional financing vehicle for scaling real estate portfolios without personal tax return documentation or W-2 debt-to-income (DTI) limitations. To master the transition from high-interest bridge financing to permanent 30-year debt, study our Hard Money to DSCR Refinance Guide and download the Free DSCR Loan Underwriting Checklist.
What is a DSCR Loan?
A Debt Service Coverage Ratio (DSCR) loan is an asset-based mortgage where loan qualification is determined strictly by the subject property’s rental revenue rather than the borrower’s personal income, employment history, or tax returns. Using our DSCR Calculator, investors can model whether a prospective acquisition or cash-out refinance generates sufficient cash flow to cover the complete monthly PITIA (Principal, Interest, Property Taxes, Hazard Insurance, and HOA dues). Both domestic investors and foreign nationals operating through a US LLC for non-US owners utilize DSCR financing to scale holdings without traditional bank friction.
How to Calculate DSCR with the DSCR Calculator
The mathematical formula used by commercial lenders and our DSCR Calculator is:
$$text{DSCR} = frac{text{Gross Monthly Rental Income}}{text{Monthly PITIA (Principal + Interest + Taxes + Insurance + HOA)}}$$
For commercial properties and larger multifamily buildings (5+ units), the formula evaluates annual property cash flows:
$$text{Commercial DSCR} = frac{text{Annual Net Operating Income (NOI)}}{text{Annual Total Debt Service (P&I)}}$$
Understanding DSCR Underwriting Tiers for Lender Approval
| DSCR Ratio | Cash Flow Status | Lender Underwriting Requirements |
|---|---|---|
| $text{DSCR} < 1.00times$ (No-Ratio) | Negative Cash Flow | Requires higher equity down payment (25%–35%), 12 months liquid reserves, and higher interest rate pricing. |
| $text{DSCR} = 1.00times text{ to } 1.19times$ | Break-Even / Thin Coverage | Standard qualification tier; requires 20%–25% down payment and 6 months PITIA liquid reserves. |
| $text{DSCR} ge 1.20times text{ to } 1.25times+$ | Strong Cash Flow Buffer | Optimal pricing tier; unlocks lowest available interest rates, maximum loan-to-value (up to 80% LTV), and expedited closing timelines. |
Long-Term Rental vs. Short-Term Vacation Rental (STR) DSCR Underwriting
When modeling cash flow in the DSCR Calculator, lenders verify gross income through distinct documentation pathways:
- Long-Term Rentals (LTR): Income is verified by an independent appraiser using Fannie Mae Form 1007 (Single-Family Comparable Rent Schedule) or an executed 12-month lease agreement.
- Short-Term Vacation Rentals (STR): Lenders underwrite vacation properties using 12 months of trailing property management statements, actual Airbnb/VRBO performance data, or AirDNA MarketMaker revenue projections.
- Unpermitted Space & ADUs: If your rental features an Accessory Dwelling Unit or bonus square footage, consult our guidelines on DSCR appraisal rules for unpermitted space.
Portfolio Scaling: Consolidating Notes with Blanket DSCR Loans
Investors holding multiple residential rentals can aggregate 5 to 25+ individual properties into a single institutional commercial mortgage. Review our detailed guide on Blanket DSCR Loans and explore our full suite of models in the Interactive Real Estate Investor Toolkit.
Fiduciary Loan Structuring with Curtis Waters, MBA
Need professional guidance to model your Debt Service Coverage Ratio or negotiate commercial debt terms in NC & SC? Let’s connect:
Professional LinkedIn: Curtis Waters Profile
Amazon Author: The Relationship Blueprint on Amazon
Direct Strategy Email: curtis@entrepreneursreport.com